The PF wage ceiling is now ₹25,000. Here is what it does to your October payslip, your CTC and your retirement money.
| Disclaimer: This article on the changes in EPFO rule is for general information only. It is not tax, legal or financial advice. Salary structures differ from company to company, so please confirm your numbers with your HR or payroll team, or a qualified advisor, before making any decision. |
Quick Answer
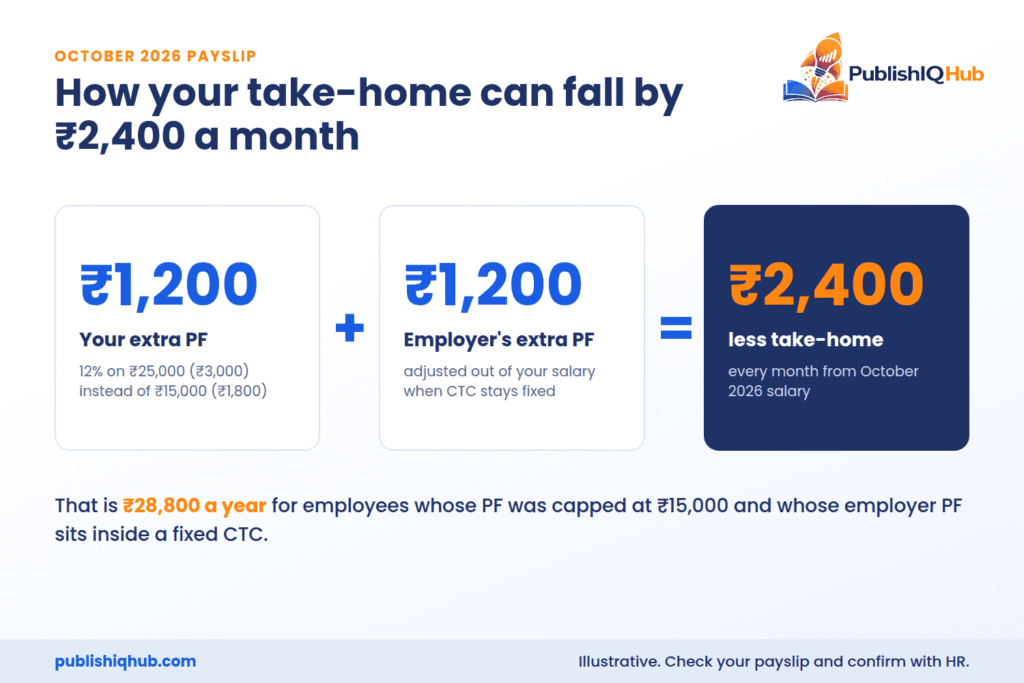
After the changes in EPFO rule, PF from October 2026 salary is calculated on Basic + DA of up to ₹25,000, not ₹15,000. If your PF was capped earlier, your deduction rises from ₹1,800 to ₹3,000, so take-home falls by ₹1,200. Under a fixed CTC where employer PF sits inside your package, the fall can be ₹2,400.
Key takeaways
- The EPFO wage ceiling has moved from ₹15,000 to ₹25,000 a month, effective 17 September 2026.
- If your Basic + DA is ₹25,000 or more and PF was capped at ₹15,000, you lose ₹1,200 a month from take-home.
- If your employer’s PF share is part of a fixed CTC, the total cut can reach ₹2,400 a month, or ₹28,800 a year.
- Employees with Basic + DA between ₹15,001 and ₹25,000 who were outside PF now come under mandatory coverage.
- The money is not lost. It goes into your PF corpus, EPS pension and EDLI insurance cover.
Your October 2026 salary lands. You open the payslip on your phone, and the net pay is lower by ₹1,200. For some of you, it will be ₹2,400. No increment was cut and no new EMI started. The reason sits in one line of the deductions column: Provident Fund.
This is the first real, rupee-level effect of the changes in EPFO rule that raised the PF wage ceiling for the first time in twelve years. Most employees will notice this impact on Indian salaried take home salary only when the credit SMS comes in, which is exactly why we want to walk you through it before that happens.
Below, we break down what changed, how PF is now calculated, three real payslip scenarios, and what you (or your HR team) should do next. We will keep it practical, with rupee numbers throughout.
What are the changes in EPFO rule? EPF wage ceiling increased from 15000 to 25000
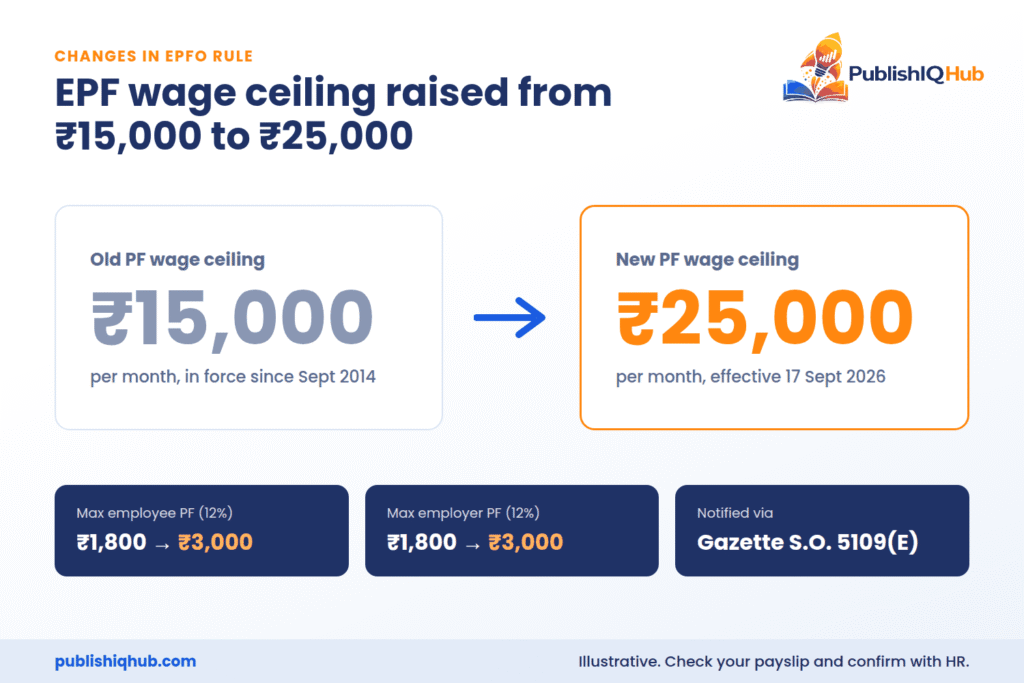
On 16 September 2026, the Union Cabinet approved raising the EPFO wage ceiling from ₹15,000 to ₹25,000 per month. The old ₹15,000 limit had been in place since September 2014, so this revision was long overdue.
The government then notified the change the very next day. As per SGCMS’s regulatory update, Gazette notification S.O. 5109(E) dated 17 September 2026 was issued under the Code on Social Security, 2020, and the new ceiling applies from that date.
What does “wage ceiling” mean in plain words? It is the maximum Basic + DA on which PF contribution becomes compulsory. Earlier, if your Basic + DA was ₹40,000, most companies calculated PF only on ₹15,000. Now that cap sits at ₹25,000.
The reach is big. SCC Online reports that over 51 lakh additional employees now come under mandatory EPFO coverage because of this revision. You can read the official scheme details on the EPFO website.
Old vs new: PF contribution at ₹15,000 and ₹25,000
Here is how the changes in EPFO rule play out side by side for an employee whose PF is calculated at the ceiling. Figures are per month.
| Component | Old ceiling (₹15,000) | New ceiling (₹25,000) | Change |
| Employee EPF (12%) | ₹1,800 | ₹3,000 | +₹1,200 |
| Employer share to EPS (8.33%) | ₹1,250 | ₹2,083 | +₹833 |
| Employer share to EPF (3.67%) | ₹550 | ₹917 | +₹367 |
| Employer PF total (12%) | ₹1,800 | ₹3,000 | +₹1,200 |
| EDLI (0.50%) | ₹75 | ₹125 | +₹50 |
| Admin charges (0.50%) | ₹75 | ₹125 | +₹50 |
| Total employer outgo | ₹1,950 | ₹3,250 | +₹1,300 |
| Total PF + EPS in your name | ₹3,600 | ₹6,000 | +₹2,400 |
The employer figures come from Corporate Professionals’ analysis, which shows the employer’s minimum PF contribution rising from ₹1,800 to ₹3,000, and total outgo including EDLI and admin charges rising from ₹1,950 to ₹3,250.
New PF rule from October 2026 salary: when does it hit your payslip?
Because the changes in EPFO rule took effect from 17 September 2026, September itself is a split month. SGCMS explains that contributions for 1 to 16 September are calculated on the ₹15,000 ceiling, and for 17 to 30 September on the ₹25,000 ceiling. September 2026 contributions, including these pro-rata amounts, are due by 15 October 2026.
So the full-month impact starts with your October 2026 payroll. If your company had already closed September payroll before the notification, the small pro-rata difference may be adjusted in October. That could make October’s dip look slightly bigger than the regular monthly figure. Your HR team can confirm how they are handling it.
How much PF will be deducted from my salary after the new rule?
The formula has not changed. Employee PF is still 12% of Basic + DA. What changed is the cap on the Basic + DA used for that 12%.
| Your Basic + DA | PF deduction earlier (capped at ₹15,000) | PF deduction now (capped at ₹25,000) | Extra per month |
| ₹12,000 | ₹1,440 | ₹1,440 | Nil |
| ₹18,000 | ₹1800 | ₹2,160 | ₹360 |
| ₹25,000 | ₹1800 | ₹3,000 | ₹1,200 |
| ₹1800 | ₹3,000 | ₹1,200 |
Two quick notes. If your Basic + DA is below ₹15,000, nothing changes for you. And if your company already deducts PF on your full Basic (many MNCs and PSUs do), your deduction stays the same.
PF calculation on 25000 basic salary
Take Basic + DA of ₹25,000. You contribute 12%, which is ₹3,000. Your employer also contributes ₹3,000, but it is split: about ₹2,083 goes to EPS (pension) and about ₹917 goes to your EPF account.
So your EPF account receives ₹3,000 plus ₹917, which is ₹3,917 every month. Corporate Professionals notes this is up from ₹2,350 under the old ceiling. On top of that, the employer pays ₹125 for EDLI and ₹125 as admin charges, which do not show in your passbook.
EPS pension contribution on 25000 wage ceiling
The EPS share is 8.33% of wages up to the ceiling. As Ujjivan Small Finance Bank explains, that works out to roughly ₹2,083 a month at ₹25,000, against ₹1,250 at ₹15,000.
Why should you care? A higher EPS wage means a higher pension later. Corporate Professionals estimates the maximum EPS pension moves from ₹7,500 to ₹12,500 a month for someone with 35 years of service. EPS eligibility can depend on your joining date and past wages, so check your status in your UAN profile or with HR.
Will my take home salary reduce due to new EPF rule?
Yes, for many salaried employees it will, though the changes in EPFO rule do not hit everyone the same way. This is the part everyone is asking about, so let us go slowly. The exact impact on Indian salaried take home salary depends on two things: how your PF was calculated earlier, and whether your employer’s PF share is counted inside your CTC.
Worked example: Rahul’s October 2026 payslip
Rahul works in Pune. His monthly Basic + DA is ₹30,000, HRA is ₹12,000 and special allowance is ₹13,000, so his gross is ₹55,000. Earlier, his company deducted PF only on ₹15,000. Professional tax is ₹200. We are keeping income tax (TDS) out to make the PF effect clear.
| Payslip line | Before (September) | October: employer PF outside CTC | October: employer PF inside fixed CTC |
| Basic + DA | ₹30,000 | ₹30,000 | ₹30,000 |
| HRA | ₹12,000 | ₹12,000 | ₹12,000 |
| Special allowance | ₹13,000 | ₹13,000 | ₹11,800 |
| Gross salary | ₹55,000 | ₹55,000 | ₹53,800 |
| Employee PF | ₹1,800 | ₹3,000 | ₹3,000 |
| Professional tax | ₹200 | ₹200 | ₹200 |
| Net pay before TDS | ₹53,000 | ₹51,800 | ₹50,600 |
| Change in take-home | Base | ₹1,200 less | ₹2,400 less |
In the middle column, Rahul’s company absorbs the extra employer PF of ₹1,200 from its own pocket. Only his own share goes up, so his net pay drops by ₹1,200.
In the last column, the company keeps his CTC fixed. Since the employer’s PF is part of his CTC as per company policy, the extra ₹1,200 employer share has to come from somewhere, and it usually comes from the special allowance. His own ₹1,200 extra deduction adds to that. Net result: ₹2,400 less every month, or ₹28,800 a year.
One small silver lining in the fixed-CTC case: gross salary falls by ₹1,200, so taxable salary also falls slightly and TDS may reduce a little.
EPF wage ceiling hike impact on in-hand salary: the three scenarios
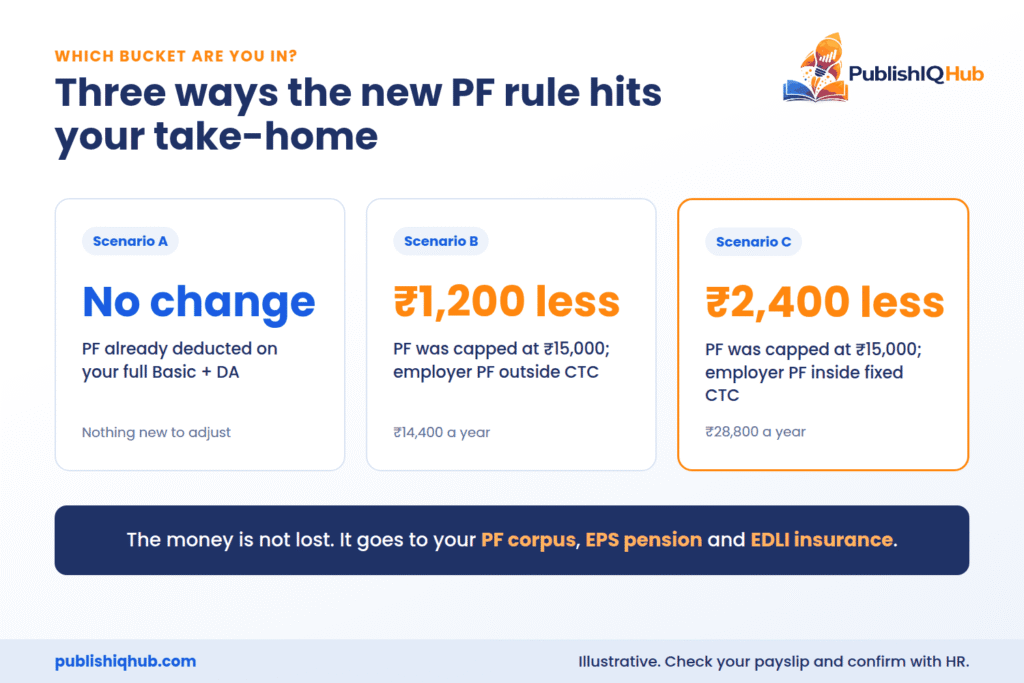
Most salaried employees will fall into one of these three buckets
| Scenario | Who it applies to | Monthly take-home change | Yearly change | Where the money goes |
| (a) PF already on full Basic | Companies that already deduct 12% on actual Basic + DA above ₹25,000 | No change | No change | Nothing new |
| (b) Employer share outside CTC | PF was capped at ₹15,000; employer bears its extra ₹1,200 separately | ₹1,200 less | ₹14,400 less | Your own EPF account |
| (c) Employer share inside fixed CTC | PF was capped at ₹15,000; CTC stays the same, employer PF is part of it | ₹2,400 less | ₹28,800 less | EPF account, EPS pension |
Ujjivan SFB also flags this: if the higher employer contribution sits inside a fixed CTC, the cash part of salary may reduce. Please treat these as illustrations. Your real figure depends on your salary structure, so check your October payslip and ask HR how they have applied it.
Earning ₹15,001 to ₹25,000 and not a PF member?
This group sees the sharpest change. If your Basic + DA was above ₹15,000 when you joined and you were never enrolled in PF, you were outside the net. That is no longer the case up to ₹25,000.
Say your Basic + DA is ₹20,000. A fresh 12% deduction of ₹2,400 starts, and your employer adds ₹2,400 on its side. If your employer counts its share inside your CTC, your take-home could reduce further. SGCMS says employers need to generate or link UANs and complete KYC and e-nomination for such employees, so expect a mail from HR if you fall in this band.
Does employer PF contribution come from my CTC?
It depends on how your offer letter is written. In many Indian companies, CTC is exactly what it says: the total cost to the company. That includes Basic, HRA, allowances, and the employer’s PF, gratuity and insurance. In such cases, when employer PF goes up and CTC stays the same, something else in your salary has to shrink.
Other employers show PF separately, over and above a “gross” figure. There, the extra employer PF is a cost the company carries, and you only feel your own ₹1,200.
The quickest way to know? Open your appointment letter or salary annexure. If you see a line like “Employer contribution to PF” inside the CTC table, you are in the fixed-CTC bucket. If you are unsure, just ask HR directly. It is a fair question and they will be getting it a lot this month.
The money is not lost: where your extra ₹2,400 goes
A lower net pay feels bad on the 1st of the month. Yet this is the side of the changes in EPFO rule that rarely makes the headlines. But the money moves into three places that work for you:
- PF corpus: Your ₹3,000 plus the employer’s ₹917 builds your EPF balance and earns interest every year.
- EPS pension: The employer’s ₹2,083 builds your monthly pension entitlement after retirement.
- EDLI insurance: The employer’s EDLI contribution funds life insurance cover for your family, with no premium from your side.
To see what this does over time, here is a simple 10-year illustration. We have used 8.25%, the EPF interest rate for FY 2025-26 that EPFO notified this year. We assume the rate and your salary stay constant, and interest is worked out on the monthly running balance and credited yearly.
| Monthly credit to your EPF account | Total contributed in 10 years | Approx. corpus after 10 years at 8.25% |
| Old ceiling: ₹2,350 | ₹2.82 lakh | ₹4.32 lakh |
| New ceiling: ₹3,917 | ₹4.70 lakh | ₹7.20 lakh |
| Difference: ₹1,567 | ₹1.88 lakh | ₹2.88 lakh |
That extra ₹2.88 lakh does not include the higher EPS pension, which is paid separately after retirement. Real returns will vary as the rate changes each year and your salary grows. Still, the point stands: the take-home you give up today comes back as savings later.
Is PF mandatory for salary above 25000?
First, remember that PF is linked to Basic + DA, not your gross or CTC. Someone earning ₹60,000 gross with Basic + DA of ₹22,000 is well within the new ₹25,000 ceiling.
Under the long-standing EPF framework, PF has been compulsory for employees whose Basic + DA is within the ceiling. Employees whose Basic + DA was above the ceiling when they joined, and who were never PF members, could generally stay out. Existing members, however, must continue contributing even if their salary later crosses the ceiling. With the ceiling now at ₹25,000, far fewer people fall into that “can stay out” group. If you think you are in it, confirm with HR, as the rules for specific cases can differ.
What salaried employees should do now
These changes in EPFO rules are already live. Here is a short action list for this month.
- Check your October payslip line by line. Compare Basic, special allowance, gross, PF and net pay with September. Note whether only your PF went up, or your allowances also changed.
- Talk to HR about CTC restructuring. Ask whether employer PF is part of your CTC and how the extra ₹1,200 has been adjusted. Some companies may offer to rebalance allowances, so it is worth asking.
- Review your tax regime. Under the old regime, your own PF counts towards the Section 80C limit, so higher PF may reduce your need for other 80C investments. Under the new regime, 80C is not available, but a lower gross in a fixed-CTC setup can slightly cut TDS.
- Decide between VPF and other investments. If you like PF’s safety, you can add more through Voluntary PF. If you already feel over-invested in debt, balance it with market-linked options. Our guide to the top stock brokers in India for investments can help you compare platforms for SIPs and direct equity.
- Update your monthly budget. Plan for ₹1,200 to ₹2,400 less in your account. If your EMIs, SIPs or rent auto-debit sit close to your net salary, shift the dates or amounts now.
New EPFO rules 2026 for employers: what HR and payroll must fix
For HR heads, payroll managers and small-business owners, the changes in EPFO rule are not only an employee-relations issue. It is a compliance deadline and a cost line.
Compliance and ECR. Update payroll software to the ₹25,000 cap from 17 September. File the September ECR with pro-rata wage calculations before the 15 October due date. Late or short payment can attract damages and interest, so reconcile the first cycle carefully.
Enrolment of new members. Identify everyone with Basic + DA between ₹15,001 and ₹25,000 who was not a member. Generate or link UANs, and complete KYC and e-nomination. SGCMS also suggests checking eligibility for employer incentives under PMVBRY.
Budget for the cost. Corporate Professionals puts the extra employer cost at ₹15,600 a year for each employee previously at the ceiling. For a team of 200 such employees, that is about ₹31.2 lakh a year. Finance teams should factor this into FY 2026-27 salary budgets.
Offer letters and CTC restructuring. Review how your CTC templates show employer PF. If you choose to keep CTC fixed, communicate the change in writing before October salaries go out. A clear note on why take-home has changed, and where the money goes, saves a lot of payroll tickets.
If your HR team is stretched, this is a good time to look at automation. Our guide on AI and human resources and the best AI HR software covers tools that handle payroll rules, employee queries and document workflows. Smaller firms that prefer to hand over payroll and statutory filing altogether can compare providers in our list of top Indian BPO companies for your business.
Final word on the changes in EPFO rule
The changes in EPFO rule mean a smaller credit on payday for lakhs of salaried Indians, but a larger safety net later. Most people at or above the ceiling will see ₹1,200 to ₹2,400 less each month from October 2026, depending on how their CTC is built. Read your payslip, ask HR the right questions, and adjust your budget and investments early.
If you are planning where to put your savings next, start with our comparison of stock brokers in India. And if you run a growing business weighing in-house payroll against outsourcing, our guide to IT outsourcing companies in India is a good next read.
Frequently asked questions
What is the new EPF wage ceiling in 2026?
The EPF wage ceiling is now ₹25,000 per month, up from ₹15,000. The Union Cabinet approved it on 16 September 2026 and it was notified through Gazette S.O. 5109(E) on 17 September 2026 under the Code on Social Security, 2020. The old limit had applied since September 2014.
From which month will the new PF rule affect my salary?
The rule applies from 17 September 2026, so September is split: the first 16 days use ₹15,000 and the rest use ₹25,000. The full-month effect shows in your October 2026 salary. Pro-rata September contributions are due by 15 October 2026, so small arrears may appear in October.
How much PF will be deducted from my salary after the new rule?
Your PF is 12% of Basic + DA, capped at ₹25,000. So the maximum compulsory deduction is ₹3,000 a month, against ₹1,800 earlier. If your Basic + DA is ₹18,000, you pay ₹2,160. If it is below ₹15,000, your deduction does not change at all.
Will my take home salary reduce due to new EPF rule?
If your Basic + DA is ₹25,000 or more and PF was capped at ₹15,000, your take-home falls by ₹1,200 a month. If your employer’s PF is inside a fixed CTC, it can fall by ₹2,400. If PF was already on your full Basic, nothing changes. Check your payslip to be sure.
Does employer PF contribution come from my CTC?
In many Indian companies, yes. CTC often includes the employer’s PF, so when that contribution rises and CTC stays fixed, allowances such as special allowance are reduced. Other companies show employer PF separately and bear the extra cost. Your appointment letter or salary annexure will tell you which structure applies.
What is the PF calculation on 25000 basic salary?
At ₹25,000 Basic + DA, you contribute ₹3,000 and your employer contributes ₹3,000. Of the employer’s share, about ₹2,083 goes to EPS and about ₹917 to your EPF account. So your EPF account gets ₹3,917 a month, while the employer also pays ₹125 each for EDLI and admin charges.
How much EPS pension contribution is made on the ₹25,000 wage ceiling?
The EPS contribution is 8.33% of wages up to the ceiling, which is roughly ₹2,083 a month at ₹25,000. Earlier it was ₹1,250 at ₹15,000. This comes from the employer’s 12% share, not from your salary directly, and it builds a higher monthly pension after retirement.
Is PF mandatory for salary above ₹25,000?
PF depends on Basic + DA, not gross salary. It is compulsory within the ₹25,000 ceiling. Employees whose Basic + DA was above the ceiling at joining, and who were never members, could generally opt out. Existing members must continue. Since exceptions exist, confirm your case with HR or the EPFO.
Is the extra PF deduction money lost?
No. The extra amount goes into your EPF corpus, which earns interest (8.25% for FY 2025-26), your EPS pension account and EDLI life insurance cover. At 8.25%, an extra ₹1,567 a month into your EPF account can grow to about ₹2.88 lakh in 10 years, assuming a constant rate and salary.